Chicago real estate
The Fed Raised Rates Wednesday for the First Time in Three Years. Your 30-Year Mortgage Didn't Move — Your HELOC Repriced This Morning.
What actually changed for Chicago and suburban homeowners on September 16, and what didn't.

What actually changed for Chicago and suburban homeowners on September 16, and what didn't.
At 2 p.m. Eastern on Wednesday, the Federal Reserve raised its benchmark rate by a quarter point, to a target range of 3.75%–4.00%. It was the first increase since July 2023, and the vote was unanimous, 12–0. The Fed's own projections released the same afternoon showed 16 of 18 participating policymakers expect at least one more increase before the end of this year, and four of them think two more is possible.
By Wednesday evening, every real estate headline in the country said some version of "rates are going up."
Here's the part that got buried: the number that changed overnight for Chicagoland homeowners wasn't the 30-year mortgage rate. It was the prime rate — and if you have a home equity line of credit on your house in Naperville or Norwood Park, yours repriced this morning.
What the Fed actually controls
The federal funds rate is an overnight lending rate between banks. It isn't a mortgage rate, and the Fed does not set mortgage rates. What it does set, almost mechanically, is the prime rate — the benchmark banks use to price a whole category of variable-rate consumer debt.
Prime has historically run about three percentage points above the top of the fed funds range. So when the Fed moved Wednesday, the banks moved with it. JPMorgan Chase, Bank of America, Citigroup, Wells Fargo, Truist, Fifth Third, Huntington and KeyCorp all raised prime from 6.75% to 7.00%, effective Thursday — today.
Prime is the index sitting underneath:
- Home equity lines of credit (HELOCs) — almost all are variable and priced as prime plus a margin
- Credit cards — most carry variable rates that track prime, and they pass changes through fast
- Personal loans, many small-business lines, and some construction loans
Your fixed 30-year mortgage is untouched. Your fixed-rate home equity loan is untouched. Your HELOC is not.
What a quarter point costs on a HELOC, in actual dollars
A quarter point sounds like nothing. On a draw balance, here's what it is:
| Outstanding HELOC balance | Added interest per year | Added interest per month |
| $50,000 | $125 | about $10 |
| $100,000 | $250 | about $21 |
| $200,000 | $500 | about $42 |
Not a crisis. But note the Fed's own dot plot: most policymakers expect at least one more increase this year, with two more meetings left on the 2026 calendar. If that happens, double the table. If both happen, triple it.
National averages heading into the decision put HELOCs around 7.26% (Bankrate, September 9) to 7.53% (Curinos), and fixed home equity loans around 8.13%. Bankrate's survey of lenders found live offers ranging from roughly 4% to 11.6%, which is a reminder that the spread between a good HELOC and a bad one is worth far more than a quarter point.
Why this matters more around here than it used to
Because a lot of Chicagoland homeowners chose the HELOC instead of the move.
Nearly half of all outstanding U.S. mortgages carry a rate of 4% or lower, and close to a fifth are at 3% or lower, according to National Association of REALTORS® data for the first quarter of 2026. Nobody with a 3% loan wants to trade it for a 7% loan. So instead of selling and buying up, people have been borrowing against the house and staying put — finishing the basement, adding the bathroom, redoing the kitchen.
The scale of that is enormous. The ICE Mortgage Monitor put total mortgage-holder equity at a record $18 trillion in the second quarter of 2026, with roughly 47.5 million mortgage holders sitting on $11.7 trillion in tappable equity — about $212,000 each, on average. Commercial banks held $287.4 billion in HELOC balances as of July 2026, the highest level of the year.
That is the debt the Fed actually just touched. Not the first mortgage.
Meanwhile, the 30-year fixed marches to a different drummer
Long-term mortgage rates track the 10-year Treasury yield and mortgage-backed securities pricing, not the fed funds rate. And the 10-year has been the real story for three weeks.
It went from about 4.80% on September 8 to 4.96% on September 11, crossed 5% ahead of the meeting — the highest since 2007 — and sat at roughly 5.02% after the announcement. Higher energy costs feeding into inflation readings have been the main pressure.
Where that leaves the actual quotes:
| Measure | 30-year fixed | As of |
| Freddie Mac PMMS (weekly survey) | 6.76% | September 10, 2026 |
| Freddie Mac PMMS, one week earlier | 6.71% | September 3, 2026 |
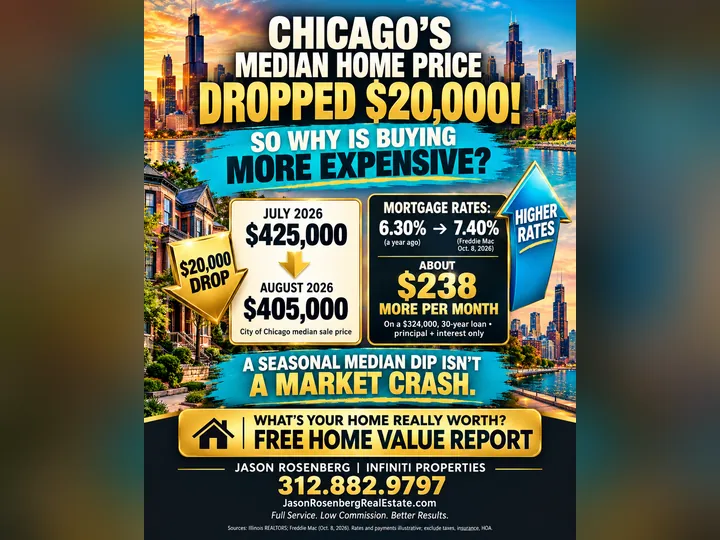
| Freddie Mac PMMS, one year earlier | 6.35% | September 2025 |
| Optimal Blue daily lock index | 7.01% | September 17, 2026 |
| Mortgage News Daily index | about 7.17%–7.19% | mid-September 2026 |
Those measure different things and are not directly comparable. Freddie Mac averages applications submitted over a week, published Thursdays at noon Eastern — the new number lands today. The daily indexes price actual rate locks for a single session, which is why they run higher and move first. If you are shopping right now, the daily number is the one closer to your reality.
The receipt from the last cycle
If you read the piece I wrote last month on why the Fed's cuts didn't lower your mortgage rate, this will sound familiar in reverse. The Fed cut 1.75 percentage points across late 2024, and the 30-year fixed went up anyway, because the bond market had already priced the cuts in and then worried about inflation.
The same logic runs the other direction. A credible inflation-fighting hike can calm the bond market, and if long yields settle, mortgage rates can drift down even while the Fed is tightening. One mortgage executive made exactly that point to CNN this week: in 2025 the Fed cut and mortgage rates rose, so there's no rule saying a 2026 hike can't be followed by rates easing.
It can also go the other way. Chair Kevin Warsh said Wednesday he would be "hard-pressed" to call current financial conditions restrictive, which markets read as leaving plenty of room for more tightening. Bond traders trimmed their initial rally after the press conference.
Nobody knows. Anyone telling you they do is selling something.
What this does to a Chicago purchase, in numbers
Chicago's median sale price over the three months ending August 2026 was $426,000, up 9.3% year over year, with homes going under contract in about 49 days and price per square foot at $289 (Redfin). Run the same purchase at 20% down — a $340,800 loan — at three different rates:
| Rate | Monthly principal & interest | Difference |
| 6.35% (one year ago) | $2,120 | — |
| 6.76% (Freddie Mac, Sept 10) | $2,213 | +$93/mo |
| 7.01% (daily lock index, Sept 17) | $2,270 | +$150/mo |
Taxes, insurance and any HOA sit on top of those figures. Flip it around and it reads worse: the $2,120 monthly payment that financed a $340,800 loan a year ago finances roughly $318,400 today. Same payment, about $22,400 less loan, roughly $28,000 less house at 20% down.
One Chicagoland wrinkle that has nothing to do with the Fed: Cook County's second-installment tax bills for 2025 went out September 1 and are due October 1. If your payment jumps this fall, check whether it's the escrow analysis before you blame the bond market.
The honest case this gets better
- The hike was almost fully priced in before it happened, so the damage to long rates may already be done.
- If the Fed convinces markets it will hold the line on inflation, the 10-year can fall — and mortgage rates follow the 10-year, not the Fed.
- Fed projections show inflation easing toward 2.3% in 2027, with GDP growth nudged up to 2.3% this year. A cooling inflation path is the single best thing that could happen to a 30-year quote.
- Higher rates thin out competing buyers. In a market where Chicago homes are still selling in about seven weeks, less competition is worth real money at the negotiating table.
The honest case this gets worse
- Most of the committee expects at least one more hike this year. Each one adds another quarter point to prime, and therefore to every HELOC and credit card balance.
- The 10-year above 5% is a multi-year high, and energy prices — the main inflation pressure right now — are outside the Fed's control.
- Higher rates deepen the lock-in effect. Fewer homeowners give up 3% loans, inventory stays thin, and thin inventory keeps prices up. Buyers can end up paying more and financing it at a higher rate.
- If you carry a variable balance, this is a cost increase that arrives whether or not you transact.
Three checklists
If you have a HELOC
- Find out whether you are in the draw period or the repayment period. Repayment-period payments include principal and will move more.
- Check your margin over prime. It's in your original agreement. Prime + 0.5% and prime + 2.5% are very different loans.
- Ask your lender whether you can convert all or part of the balance to a fixed rate. Many HELOCs have this feature and most borrowers never use it.
- If the balance is large and you have no plans to move, price a fixed home equity loan against it.
- Don't panic-pay it off with cash you'll need for a down payment.
If you're buying right now
- Get a fresh pre-approval. One from July is no longer accurate.
- Ask your lender for the lock cost and the float-down option in writing, on the day you ask.
- Quote at least three lenders on the same day. A quarter point on a $340,000 loan is about $57 a month, and lender spreads are routinely wider than that.
- Ask about a seller-paid rate buydown. With more homes taking price reductions than they were a year ago, a 2-1 buydown can be easier to get than a price cut.
- Watch your credit card balances. Prime just went up, minimum payments follow, and your debt-to-income ratio is measured at underwriting.
If you're selling this fall
- Price to today's buyer payment, not to August's. The affordability math changed under your feet.
- Ask your agent for the actual days-on-market and sale-to-list numbers for your specific town and property type — citywide medians blend condos, townhomes and houses and will mislead you.
- Consider offering a buydown credit instead of a price reduction. It often costs the seller less and moves the buyer's payment more.
- If your buyer's financing is adjustable or they're carrying a HELOC on a current home, build in extra time for underwriting.
- If you have a Senior Freeze or other exemption, remember it does not transfer to the buyer — which matters for how the tax proration gets negotiated.
What I'd watch over the next two weeks
- Freddie Mac's weekly number, today at noon Eastern. It's the first survey reading that captures the days around the decision.
- The 10-year Treasury. If it settles back under 5%, mortgage quotes ease. If it grinds higher, they don't.
- Illinois REALTORS® August data, due September 24. July had the city median at $425,000, up 13.3%, on inventory down 26.3%. August will tell us whether the supply squeeze held.
Where I fit in
When financing costs move, the cost of selling matters more, not less. I list at 1.25% on the listing side — on a $426,000 sale that's about $5,325. Commissions are negotiable and vary by brokerage, so compare mine against whatever you're quoted. Two other things go with it: a Zero Commission Clause, meaning you owe me nothing if you find your own buyer, and a cancel-anytime policy with no lock-in.
That's the lower rate attached to full service — professional photography, 3D Matterport tours, and full online marketing — not a stripped-down listing.
If you want to know what your house is actually worth in this market, or what a payment looks like on a specific property at today's number, call or text me at 312.882.9797. I serve Chicago and the entire Chicagoland area.
Sources
- Federal Reserve, FOMC statement and Summary of Economic Projections, September 16, 2026
- CNBC, "Fed rate decision September 2026," September 16, 2026
- CNBC, "10-year Treasury yield climbs back to 5% after Fed hikes rates," September 16, 2026
- Reuters, "Major US banks raise prime rate after first Fed rate hike since 2023," September 16, 2026
- Fox Business, coverage of Chair Warsh's post-meeting press conference, September 16, 2026
- Saxo / FXStreet, "Fed review: the hike was expected, the message was more hawkish," September 17, 2026
- CNN Business, "The Fed just raised rates. Here's what it means for borrowers and savers," September 16, 2026
- Freddie Mac, Primary Mortgage Market Survey, September 3 and September 10, 2026
- Optimal Blue (OBMMI) via MortgageDaily.com daily rate report, September 17, 2026
- Mortgage News Daily, 30-year fixed rate index, mid-September 2026
- CBS News, "What a Fed rate hike could mean for mortgage rates," September 2026 (10-year Treasury movement, Federal Reserve data)
- Bankrate, HELOC and home equity loan rate surveys, September 2, 2026 and September 9, 2026
- Curinos, HELOC and home equity loan averages, September 2026
- ICE Mortgage Monitor, Q2 2026 equity figures
- Federal Reserve Board of Governors, commercial bank HELOC balances, July 2026
- National Association of REALTORS®, share of outstanding mortgages by rate, Q1 2026, via PBS News
- Redfin, Chicago housing market data, three months ending August 2026
- Illinois REALTORS®, July 2026 home price and sales report (released August 20, 2026)
- Cook County Treasurer, second-installment tax year 2025 billing schedule
This article is general information, not financial or lending advice. Mortgage rates, HELOC terms and margins vary by borrower and lender. Talk to a licensed loan officer about your specific situation.
Let’s talk
Thinking about buying or selling?
Call or text Jason directly. Full-service real estate, lower commission, anywhere in Chicago and the Illinois suburbs.